
The decisive moment for a Las Vegas hotel-casino this week was not a ribbon cutting or a rebrand. It was a judge in Clark County District Court signing off on a transfer of assets out of a receivership estate, and in doing so overruling the people who stood to lose from it.
That makes the Downtown Grand sale a useful test case, because it is the kind of casino ownership acquisition that gets filed under “consolidation” and “investor confidence” when the underlying documents say something narrower and more interesting. The numbers that exist here permit one clear claim: a court cleared the legal path for Vegas Ventures LLC to take the assets. They do not permit any claim at all about what casino real estate is worth right now, because the price was never disclosed.
What the Clark County order actually authorises
A district court judge approved the sale of the Downtown Grand hotel-casino to Vegas Ventures LLC and authorised the court-appointed receiver, Paul Huygens of Province LLC, to transfer the assets of the receivership estate. The judge rejected objections from limited partners connected to the property’s junior secured lender. The purchase price does not appear in the court filings, and attorneys for the receiver did not immediately respond to a request for comment, according to the Las Vegas Review-Journal’s reporting on the ruling.
Two details in that paragraph carry most of the weight. First, the seller is a receiver, not an owner choosing to exit. Second, the objectors were subordinated creditors, not rival bidders. Neither fact fits the standard M&A narrative of a buyer paying up for a strategic asset.
“Free of liens” is the phrase doing the work
Under the order, the assets transfer free of liens and other claims, with the applicable interests attaching instead to the sale proceeds. In plain terms, the buyer gets the property without inheriting the debt that sits on it, and the lenders get to fight over the cash that comes in.
That structure explains the objection. When claims move from the asset to the proceeds, the recovery available to each creditor is capped by whatever the sale actually raised and by where that creditor sits in the queue. A senior lender is usually made whole or close to it. A junior secured lender, and the limited partners behind it, may find there is very little left under them. Objecting to the sale is one of the few levers such a party has, and in this instance the court did not accept it.
For anyone reading casino industry M&A headlines, that is the first correction to make. A contested sale approval is not a signal that the market priced an asset well. It is a signal that a court decided the process was adequate and that the clock had run out on the arguments against it.
A construction loan failed, not the casino floor
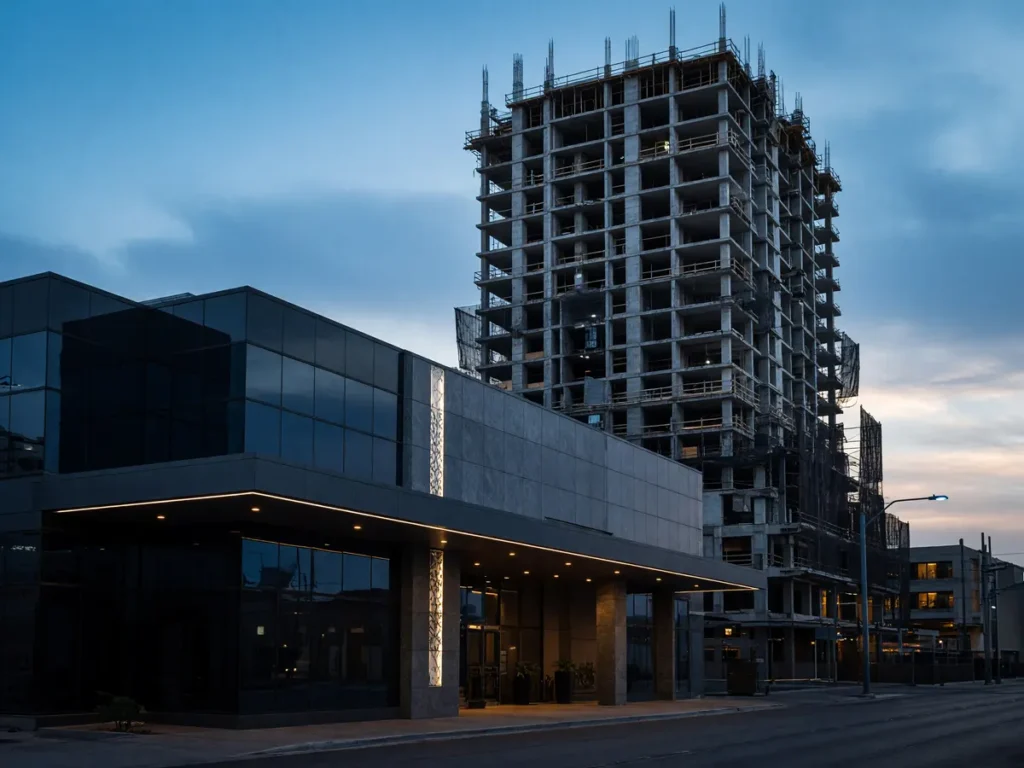
The Downtown Grand has been in receivership since January, after a default on a construction loan used to finance a new hotel tower. Banc of California sued the property’s ownership entities in December in connection with that loan.
This is the part worth sitting with, because it points at a specific risk rather than a general malaise. The trigger was development finance on an expansion project, not a collapse in gaming revenue. Those are different failure modes with different implications. Operating weakness shows up as declining handle, thinner margins and eventually closures, which is the pattern behind the UK casino closures driven by rising gambling duty. A construction loan default shows up as a balance sheet problem: interest costs, cost overruns and a tower that has to be delivered and filled before it services its own debt.
Land-based casino trends get discussed as if demand were the only variable. For a property mid-expansion in a high interest rate environment, the cost of capital is the variable that bites first.
Why this casino ownership acquisition tells you less about valuations than it looks like it does
You cannot calculate a multiple from an undisclosed price. That sentence should end most of the analysis that gets written about deals like this one. Without a price, there is no EBITDA multiple, no per-key figure for the hotel rooms, no implied value per gaming position, and therefore no data point for anyone benchmarking Las Vegas casino investment.
What you can take from it is directional, and the direction is about process rather than price:
- Distressed casino assets in Nevada are transacting, and courts are willing to clear them over subordinated objections.
- Buyers exist for downtown Las Vegas property that comes without the existing debt attached.
- Lender patience on stalled or underperforming development finance has limits measured in months, not years.
That is a real finding. It is not the same as “investors are confident in casino assets,” and conflating the two is how people end up reading a receivership as a boom.
The approval that still has to come
Court approval settles who owns the assets, not who may run a casino on them. Nevada handles gaming licensing through the Gaming Control Board and the Gaming Commission, which assess the suitability of owners and operators on their own timeline and against their own standards. A judge clearing a transfer removes a civil obstacle; it does not substitute for a licensing finding.
For readers tracking the crossover between land-based assets and online operations, that two-track structure matters more than the deal itself. Regulatory suitability is the gate that determines whether a new owner can extend a casino brand into adjacent products at all, which is why ownership changes in licensed jurisdictions move slower than the press release cycle suggests. It is also why some buyers of distressed property are real estate investors first and gaming operators second, with no intention of ever holding the licence themselves.
What is still unresolved
Three things stay open after this ruling. Whether the sale proceeds cover enough of the debt stack to satisfy anyone below the senior lender. What Vegas Ventures intends to do with the unfinished expansion that caused the default in the first place. And whether the price, once it surfaces in any form, supports or undercuts the assumption that downtown Las Vegas property is holding its value.
Until the figure is public, the honest position is that this is a credit story wearing an M&A headline. Readers who follow the economics of land-based casinos and their local impact will recognise the pattern: the operating business and the financing structure on top of it can fail independently, and only one of them did here.
If you gamble at properties like this one, none of the above changes your odds by a single basis point. House edge is set by game rules, not by who holds the deed. Set a deposit or loss limit before you play, and use the self-exclusion and cool-off tools your operator is required to offer.