
The short version: backend deals change your game list, not your odds
iGaming platform partnerships are commercial deals between a casino operator and the technology firms that supply its games, wallet and back office. They widen the game menu, and when the provider is competent they help keep the site online. They do not alter the house edge on any game you open, and they are not a safety rating.
Now the complication, and it is a useful one. The Alea and ALL IN Platform story that prompted this piece is not a technical deal at all. It is a golf tournament.
What Alea and ALL IN Platform actually announced
According to Focus Gaming News, the two companies are staging the second edition of The Battle for Rome Continues at Marco Simone Golf & Country Club on 2 November 2026. Around 50 senior iGaming figures are expected, 25 per side, after the first edition finished in a 4.5–4.5 draw. The invitation-only tournament is followed by an evening reception, an awards presentation and a banquet dinner, with mind reader and mentalist Matt Daniel-Baker on the evening programme. The report describes an event for executives and strategic partners. It does not describe a new integration, a game-count milestone or any change to either company’s technology.
I am spending a paragraph on that because the lesson sits right there. A large share of what reaches players as “partnership news” is relationship building between B2B companies: conferences, sponsored lounges, awards nights, golf days. It tells you who talks to whom. It tells you nothing about whether a casino pays out.
What an iGaming platform partnership actually is
A genuine platform partnership is a licensing arrangement: the operator pays a technology supplier for software it does not want to build, and the supplier takes a share of revenue or a fee. The three common shapes are a direct deal with a single game studio, a deal with an aggregator that resells many studios at once, and a full platform or white-label contract covering the casino software itself. None of these is a marketing tie-up, which is where the golf day belongs.
Aggregator deals versus direct studio integrations
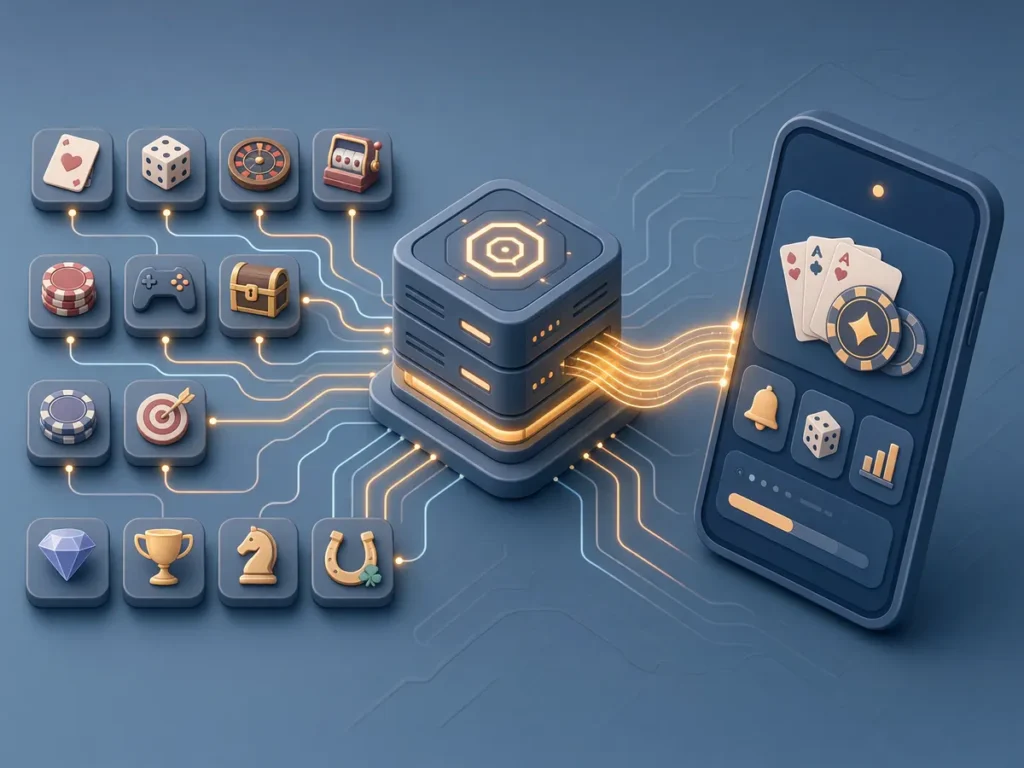
A direct integration connects the operator to one studio’s game server. An aggregator sits in between: one contract, one technical connection, and behind it the catalogues of dozens or hundreds of studios. That is the whole commercial argument for online casino aggregator platforms, and it is also their weakness, since everything then depends on one middle layer.
| Deal type | What the operator licenses | Main trade-off |
|---|---|---|
| Direct studio integration | One supplier’s games, connected to the operator’s wallet | Best control and commercial terms; slow to scale across many studios |
| Aggregator | Multi-studio content through a single API and wallet connection | Fast catalogue growth; a shared dependency and an extra revenue share |
| Platform / white label | The casino software itself: accounts, payments, bonusing, reporting | Launch speed; limited ability to differentiate from sister brands |
Why operators buy instead of build
Building a casino platform in-house means writing the wallet, the bonus engine, the reporting, the responsible-gambling tools and the regulatory reporting feeds, then recertifying all of it for every market you enter. Licensing that stack costs revenue share but removes years of engineering and a permanent compliance team. For a mid-size operator the maths is not close, which is why the supplier side of this industry is crowded and the operator side keeps outsourcing.
How one integration adds hundreds of games
Game supplier integration works through a shared API and a single wallet connection. The operator’s system holds the player balance; when a round is played, the game server asks the operator’s wallet to debit the stake and credit any result, and the aggregator routes that traffic for every studio it carries. Once that pipe exists, adding a new studio is largely a configuration and contracting exercise rather than new engineering, which is how a casino can go from a few hundred titles to a few thousand inside a quarter.
Two caveats worth holding on to. Content rights are market-specific, so a studio in the aggregator’s catalogue may still be geo-blocked where you play. And the operator decides which titles to switch on, so two casinos using the same aggregator can look very different, while two casinos using different aggregators can look nearly identical. This is the same mechanism behind the bigger aggregation deals you see reported, such as the Stake and EveryMatrix casino game aggregation partnership.
Does the reliability argument hold up?
Partly. Established platform providers run redundant infrastructure, monitored failover and load capacity sized for peak traffic, which an operator running its own servers often cannot match. Against that, concentration creates a single point of failure: when an aggregator has an incident, the player does not lose one game, they lose every studio behind that connection at once. Spread across suppliers, an outage is a gap in the lobby. Concentrated, it is an empty lobby.
Fairness testing is separate from all of this, and the distinction matters. RNG certification is performed on the game and its random number generator by accredited independent test houses such as GLI or eCOGRA, under rules set by the licensing regulator, not by the aggregator that distributes the title. An aggregator can move a certified game to more casinos. It cannot make an uncertified one trustworthy. If you want to verify a specific claim, the regulator’s own supplier or game register is the place to check, not the press release.
What changes on your screen, and what stays invisible
Visibly: more titles, new live dealer tables, sometimes faster lobby loading and better search and filtering. Invisibly: where the wallet calls are routed, which company reconciles the numbers, who hosts the game server, how bonus logic is calculated. None of that reaches you except as uptime.
So does a bigger game library mean a better casino? No. Library size is a procurement decision, and for players in India it is close to meaningless as a comparison tool, because the same aggregator catalogues appear across dozens of offshore brands targeting the same market. What separates those brands is conduct: the licence they hold, how KYC is handled, whether withdrawals land in the stated window, whether deposit and loss limits are easy to set. A partnership announcement speaks to none of that. I would not weight it at all when choosing where to play.
A checklist for reading the next partnership headline
- Confirm the operator’s licence on the regulator’s own register, not on the casino’s footer badge.
- Open a game’s information panel and check that the provider name and RTP are published, and that the figure matches the studio’s own spec.
- Look for independent test-house certification of the games and RNG, and check which jurisdiction that certification covers.
- Search recent player complaint threads for withdrawal delays and account verification disputes; patterns matter more than single reviews.
- Read the announcement for what it actually says. A new aggregator integration is operational news. A golf day is networking.
The same filter applies to the other end of the supply chain, where a studio signing a deal in a licensed market, such as Kendoo’s launch with Starcasino in Belgium, tells you something concrete about where its games are legally approved to run.
What to do with the next iGaming platform partnerships story
Treat it as weather, not as a recommendation. Backend deals genuinely shape what you can play and how reliably the site stays up, and the consolidation behind them is real. But the questions that decide whether a casino is worth your money are licensing, payout behaviour and how it treats a player who asks for their balance back, and no supplier announcement answers any of them. Vet the operator yourself, play only on a licence you can verify, set deposit and time limits before your first session, and remember that every game on every one of those catalogues carries a house edge that no partnership changes.