
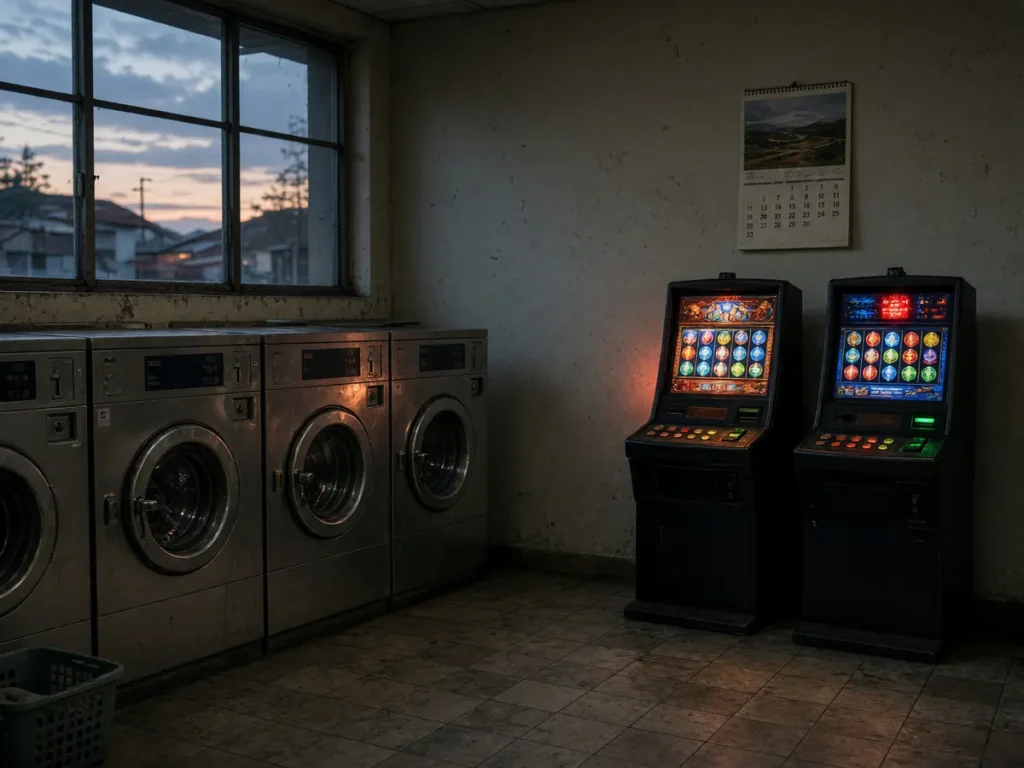
A laundromat on the second Wednesday of the month
Somewhere in West Virginia there is a laundromat with three or four slot-style video lottery terminals lined up between the change machine and the door. Most days they tick over quietly. On the second, third and fourth Wednesdays of the month, according to new research out of West Virginia University, they do not.
That is the short version of the finding: gambling spikes on payday, and the dates that matter in this particular dataset are the ones the Social Security Administration uses to deposit monthly benefits. The research comes from Matt Mullis, a fourth-year economics PhD candidate at WVU who works with the university’s Center for Gaming Research and Development, and it was reported by casino.org. Mullis says he identified direct statistical evidence tying disbursement dates to surges in gaming revenue.
Here is where I will plant a flag. The finding is credible and it is useful, but it is a finding about machines and calendar dates, not about people and their character. The coverage does not put a number on how large the spike is, and revenue data cannot tell you whether a lot of people each spent a little more or a few people spent a great deal. Treat it as a prompt to check how your own spending plan is anchored, and not as a verdict on 71 million benefit recipients.
What the West Virginia gambling behavior study actually measured
The study analysed daily, machine-level revenue reports from West Virginia video lottery terminals across 2024 and 2025, then lined those daily figures up against the Social Security payment calendar. The granularity is the interesting part. As Mullis told WVU Magazine, “If you pointed out a machine in the state, we could tell you exactly how much money that machine got on a certain day.”
West Virginia is an unusually good laboratory for this. The state has a lottery, casinos and racinos, charitable gaming, and retail and online sports betting, plus the so-called Hot Spots: bars, restaurants, lounges, social clubs and laundromats that each house a handful of video lottery machines. Those machines sit in the places people already go, which means a revenue bump shows up without anyone needing to drive to a casino.
Social Security pays on a staggered schedule tied to birth date, which gives the data three separate test dates each month rather than one.
| Birth date | Payment day |
|---|---|
| 1st to 10th | Second Wednesday of the month |
| 11th to 20th | Third Wednesday of the month |
| 21st onward | Fourth Wednesday of the month |
That staggering matters methodologically. If the revenue bump followed the first of the month, you could blame rent cycles, pension dates, anything. Following three different Wednesdays, keyed to birth dates, is a much harder coincidence to explain away.
What the reporting does not give is a magnitude. No percentage, no dollar figure, no peer-reviewed paper to check the confidence intervals against. Doctoral research reported through a university magazine and a trade news site is not the same thing as a published result, and anyone quoting a precise spike size from this work is quoting something that has not been made public. The direction of the effect is the claim. The size of it is still open.
Why income timing moves gambling activity
Money that has just landed is spent differently from money that has been sitting in an account for three weeks. Behavioural economics has two reasonably well-established explanations for the payday effect, and they stack.
The available funds effect
Spending tracks liquidity, not just income. A person with the same monthly budget behaves differently on the day the balance refills, because the constraint that was doing the disciplining has temporarily lifted. Discretionary purchases of every kind cluster in the days after money arrives, and gambling is a discretionary purchase. There is also a timing wrinkle: the gap between funds landing and plans forming is the window where impulse has the least competition. Nothing else has been earmarked yet.
Mental accounting and why windfalls get treated differently
People keep money in mental buckets. Rent money, grocery money, fun money. These buckets are not interchangeable even though the currency is, which is why someone will carefully protect a savings account while carrying a credit card balance at 20%. Benefit payments, bonuses and tax refunds are especially prone to being filed as something other than ordinary income, and whatever lands in the loosest bucket gets spent on the loosest terms.
Worth saying plainly: none of this is unique to gambling or to benefit recipients. It is how household spending works. The study’s contribution is showing the pattern cleanly in machine data, not revealing some previously hidden vice.
Does the same payday gambling pattern apply to wages?
Probably, but the study does not show it, and I am not going to pretend otherwise. The West Virginia data covers benefit payment dates specifically. Extending the finding to fortnightly salaries, monthly wages or gig platform payouts is a reasonable hypothesis, because the behavioural mechanisms behind it have nothing to do with the source of the money, and it is a hypothesis this research was not designed to test.
There is also a structural reason to expect the effect to look blurrier with wages. Social Security pays on three fixed Wednesdays, so the signal concentrates. Salaries land on dozens of different dates across an employed population, and gig earnings trickle in almost continuously. Same psychology, flatter curve, harder to see in the revenue reports.
When a payday bump turns into loss chasing
Spending more on entertainment in the week you get paid is not, by itself, a warning sign. What matters is what happens when the entertainment budget runs out before the month does. The honest answer to “is gambling more after payday a bad sign?” is: not inherently. It is the behaviour in the following three weeks that tells you something.
Loss chasing is the specific pattern to watch for. It means increasing stakes or session length to recover money already lost, on the reasoning that a win is due. It is not due. Slot and video lottery outcomes are produced by a random number generator and each round is independent of the last, so a losing streak carries no information about the next spin. The house edge applies to every round equally, which is why chasing reliably converts a small loss into a larger one.
The signs worth taking seriously:
- Depositing or spending past the amount you decided on before you started
- Returning to recover a specific loss rather than to play
- Dipping into money assigned to rent, bills, food or medication
- Borrowing, from a card, an app or a person, to keep playing
- Timing play around when funds arrive rather than when you want to play
- Hiding the size or frequency of sessions from people close to you
One counterweight deserves a mention, because it complicates the easy reading of this study. The 2023 report Gambling and Aging: An Overview of a Risky Behavior, published in PMC, found that older gamblers aged 65 and over have greater difficulty recovering from the consequences of gambling disorder, including its health complications, than younger groups. Separately, New York Council on Problem Gambling data indicates 80% of older gamblers report gambling for entertainment and enjoyment, while 38% say they gamble to distract themselves from everyday problems. Higher participation does not automatically mean higher harm, and it does not mean lower harm either.
What timing data could change for operators and regulators
If gambling revenue reliably spikes on known dates, then harm-reduction measures can be scheduled rather than left to chance. That is the practical policy implication, and it is a modest one. Deposit limits, loss limits and session reminders already exist in most regulated markets; what timing research adds is a reason to surface them when they are most likely to be relevant, and a reason for regulators to look at venue placement in locations people visit for other errands.
I am sceptical of how far this goes with machines in a laundromat. A pop-up reality check works on a logged-in online account; a video lottery terminal in a bar has no idea who is standing in front of it. The timing insight is cleaner than the intervention it implies, and that gap is where this research will either turn into policy or stay a paper.
Anchoring the budget to a plan, not a balance
The fix for a payday spike is deciding the amount before the money arrives, not after. Everything else follows from that.
- Set the monthly gambling figure while the account is empty, when the number feels like a cost rather than a share of a windfall.
- Move essential money out first. Bills, rent and groceries should leave the account before anything discretionary is considered.
- Use the operator’s deposit and loss limits, set to that figure. A limit you set in advance beats willpower you need at 11pm.
- Set session time reminders, since time spent tends to drift further than money spent.
- Treat the urge to recover a loss as a signal to stop for the day, not a signal to continue.
- If limits keep getting raised, use a cool-off or self-exclusion period instead of another limit.
Support exists if any of this feels close to home. In the United States, the National Council on Problem Gambling runs the National Problem Gambling Helpline on 1-800-522-4700, also reached as 1-800-MY-RESET; 1-800-GAMBLER is a separate problem gambling help network rather than the Council’s current helpline number. Most licensed operators also link their state’s treatment services directly from the account settings page. One caution: verify who you are calling before you hand over financial details, because the support sector has had its own integrity problems, and it is worth knowing how to check that a problem gambling support service is legitimate.
The open question in this research is not whether money arriving changes behaviour. It plainly does, in every spending category anyone has ever measured. The question is whether the spike reflects a lot of people enjoying a monthly treat or a smaller group losing more than they can afford on a predictable schedule, and machine revenue reports cannot tell those two stories apart. Until someone can, the only person who knows which story applies is the one deciding what to do on the Wednesday the money lands.