
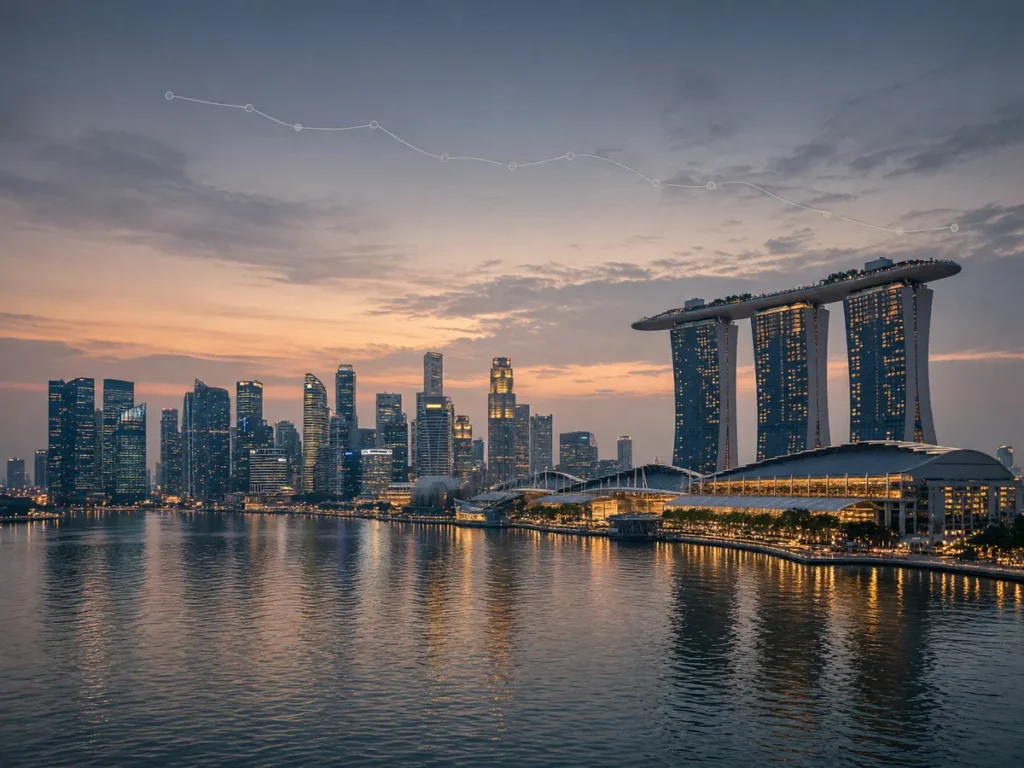
Walk the arrivals hall at Changi on a weekday morning and nothing looks like a downturn. The queues are long, the taxi rank keeps moving, and the shuttle buses to the two resorts fill up. Zoom out to the nine-month total and a small minus sign appears.
A 1.7% dip, and the mistake most readers make with it
Singapore recorded 12.7 million visitor arrivals from January to September 2026, down 1.7% year on year, according to GGRAsia’s report on the official tourism figures. That is the entire headline, and it is a far smaller signal than it is usually made to carry. For anyone comparing a destination casino trip with playing online, the useful lesson in casino resort tourism trends is not that Singapore is slipping, but that visitor headcount and gambling demand are two different measurements that happen to sit next to each other in the same press release.
A 1.7% decline on a base of 12.7 million works out to roughly 220,000 fewer arrivals across nine months, which implies a prior-year figure near 12.9 million. In an economy that moves millions of travellers a quarter, that is inside the range of ordinary fluctuation: a softer flight schedule, a weaker source-market currency, a big event that landed in a different month this year. It is not a collapse, and treating it as one is how people end up drawing conclusions the data cannot support.
What the nine-month figure actually reports
The source data covers one metric over one window: total visitor arrivals to Singapore for the January to September 2026 period, reported as 12.7 million and 1.7% lower than the same nine months of 2025. That is it. GGRAsia’s report attributes the count to Singapore’s official tourism data.
What the figure does not contain matters as much as what it does. It is not a market-by-market breakdown, so any claim about which source countries softened is guesswork unless you have the underlying table in front of you. It does not separate leisure travellers from business and MICE delegates. It does not count how many of those 12.7 million people set foot on a casino floor, and it says nothing at all about what they spent once they did. Casino tourist arrivals are a subset of total arrivals that no headline number isolates for you.
Why integrated-resort visitor numbers move in the first place
Visitor volumes at any integrated resort destination move because travel itself is price sensitive, seasonal and competitive. The main drivers are mundane:
- Airfare and hotel rates, which rise and fall with capacity, fuel costs and peak-season demand
- Exchange rates, which change how expensive a Singapore trip feels to someone earning in rupiah, ringgit, renminbi or rupees
- Regional competition, with Macau’s recovered mass market, Manila’s resort cluster, South Korea’s foreigner-only venues and Japan’s first integrated resort development all competing for the same discretionary trip
- Flight access and visa policy, which decide how easy the journey is before price even enters the conversation
- Event calendars, since a single large concert residency, sports fixture or trade exhibition can shift a month’s numbers on its own
- Broader travel demand cycles and any geopolitical disruption that makes people postpone long-haul plans
None of these is gambling-specific. A 1.7% move explained by any combination of them tells you about the cost and convenience of travel, not about appetite for baccarat.
Marina Bay Sands and Resorts World Sentosa: gaming against everything else
Singapore’s two licensed integrated resorts, Marina Bay Sands and Resorts World Sentosa, are the reason the country’s tourism figures get read as gaming figures at all. Both are built as full destinations rather than casinos with rooms attached: hotels, convention and exhibition space, retail malls, restaurants, theatres, and in Sentosa’s case theme-park and aquarium attractions. The casino floor is one profit centre among several, and it is the only one that most visitors never enter.
Gaming is the larger single contributor at both properties, which is why operator earnings calls lead with it. Putting an exact split on gaming versus non-gaming revenue is where the evidence available here runs out. The two resorts report through different corporate structures, on different calendars, and the mix shifts quarter to quarter with hotel occupancy, event bookings and the VIP cycle. A clean percentage would be easy to write and impossible to defend, so treat any single figure you see quoted as a snapshot of one reporting period rather than a standing ratio. If you want the real number, go to the operator’s own filings for the specific quarter.
Arrivals are not demand, and the gap between them is where money is made
A drop in visitor arrivals cannot be read as a drop in gaming revenue, because gaming revenue is a product of how many people play, how much they stake, and how the house edge grinds against that volume over time. Headcount is one term in that equation and not the dominant one.
Resorts have repeatedly reported higher gaming revenue in periods when visitation was flat or lower, because spend per visitor rose, or because the mix tilted towards higher-stakes play. The reverse happens too: more visitors, thinner margins, a bad run of VIP hold. The structural story behind that split is visible in markets across the region, where the shift between mass gaming and VIP revenue has moved results far more than door counts have. If you want to understand what a revenue figure means at all, it helps to know how casino gross gaming revenue is actually calculated before attaching a narrative to it.
The cost of getting this wrong is concrete. Read a 1.7% arrivals dip as evidence that destination gambling is in decline and you misjudge an entire market on a number that was never measuring it. Read it as evidence that online play is “winning” and you have invented a causal link that the data does not contain.
The trip and the account: what each one actually asks of you
A destination casino trip and an online casino session are not substitutes competing for the same spend so much as two different purchases. One buys an experience with gambling inside it. The other buys gambling with no experience around it.
| Factor | Destination resort trip | Online play |
|---|---|---|
| Upfront cost | Flights, hotel, food, transfers before a single bet | Deposit only |
| Time commitment | Days, planned in advance | Minutes, unplanned |
| Availability | Fixed to travel dates and entry rules | Continuous, which is also the risk |
| Game range | Limited by floor space | Thousands of titles, RTP usually published |
| Rewards | Comps: rooms, dining, show tickets | Bonuses carrying wagering requirements |
| Non-gambling value | Hotel, dining, shows, attractions | None |
The reward comparison is the one most often spun. A resort comp arrives after play, as a room or a meal, and its value is obvious. An online bonus arrives before play with a playthrough condition attached: a 30x requirement on a 1,000-unit bonus means 30,000 must be wagered before any withdrawal, and game weighting decides how fast that clears. Neither is free. Both are marketing spend priced against the house edge.
The honest difference is friction. A trip puts distance, cost and a return flight between you and the tables. An account removes all three. That is the accessibility online play is sold on, and it is the same property that makes limits worth setting.
Reading the trend without over-reading it
One nine-month figure, moving 1.7%, is a data point and not a direction. If you are weighing a resort trip, the number that should influence you is the airfare and the room rate, not the national arrivals total. If you play online, nothing in Singapore’s tourism data changes the arithmetic of your sessions, where a 96% RTP game still carries a 4% house edge over the long run and every round is independent of the last.
What the next quarter does to that 1.7% is genuinely unknown, and anyone offering you a confident figure for it is guessing. Set a deposit or loss limit before you play, treat the spend as entertainment rather than income, and use the operator’s cool-off and self-exclusion tools if play stops feeling like a choice.